A business can generate impressive sales and still run out of money. The problem often isn’t revenue but how quickly cash disappears compared with how much actually enters the bank account. Understanding how to calculate business burn rate helps entrepreneurs identify that risk before unpaid bills become an emergency.
Burn rate measures the cash a company consumes over a specific period, usually one month. For startups, growing companies, and small businesses operating on limited reserves, this number determines how long operations can continue without additional funding.
The calculation is straightforward. Making smart decisions with the result requires a closer look at spending, incoming payments, and future obligations.
What Business Burn Rate Reveals About Financial Health
Burn rate shows how quickly a company uses its available cash to finance operations. Unlike accounting profit, it focuses on money actually entering and leaving the business.
A software startup might spend heavily on engineers before attracting paying subscribers. A neighborhood retailer might purchase inventory months before collecting enough sales to cover those costs.
Both businesses can experience substantial cash consumption despite having promising long-term prospects.
The FDIC’s Money Smart for Small Business program, developed with the Small Business Administration, identifies cash flow management as an essential competency for business owners.
FDIC
Monitoring burn rate helps entrepreneurs determine whether spending is sustainable, whether additional funding is necessary, and which expenses deserve closer scrutiny.
Gross Burn vs. Net Burn: Two Numbers Every Owner Needs
Business burn rate has two main variations. Each answers a different financial question.
Gross Burn Rate: How Much Cash Goes Out?
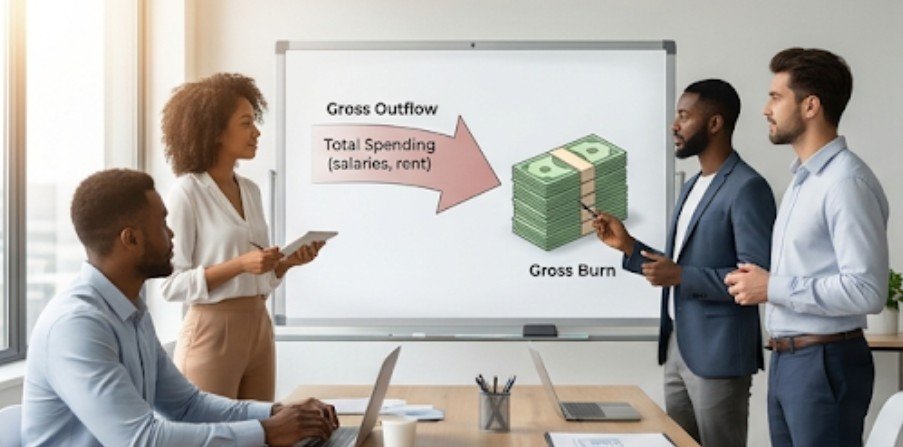
Gross burn rate represents total monthly cash spending without subtracting customer payments.
Gross Burn Rate = Total Cash Outflows ÷ Number of Months
Suppose a small technology company spends:
- Employee salaries and benefits: $45,000
- Office expenses and utilities: $10,000
- Marketing and advertising: $12,000
- Software and professional services: $8,000
- Other business payments: $5,000
Total monthly gross burn is $80,000.
Gross burn helps owners understand the cash required to maintain their current operations, regardless of sales performance.
Net Burn Rate: How Much Cash Is Actually Disappearing?
Net burn accounts for operating cash receipts and reveals how much cash a business consumes after receiving customer payments.
Net Burn Rate = Monthly Cash Outflows − Monthly Operating Cash Inflows
Using the same business:
Monthly spending: $80,000
Customer payments received: $20,000
Net burn: $80,000 − $20,000 = $60,000 per month.
The company consumes $60,000 of its available reserves monthly.
If customer receipts exceed spending, net burn becomes negative, indicating positive operating cash generation under this simplified calculation.
How to Calculate Business Burn Rate Using Actual Records
Accurate calculations begin with reliable financial records rather than estimates or expected sales.
Maintaining accurate records starts with keeping personal transactions separate from company spending, and learning how to separate business and personal expenses correctly can help entrepreneurs track operating costs and calculate their cash burn more reliably.
Step 1: Select a Meaningful Measurement Period
Start with three months of financial activity. A longer period can reveal spending patterns that one unusually expensive month might hide.
For seasonal businesses, examining an entire operating cycle may provide more representative results.
Step 2: Identify Cash Payments
Review business bank statements, payroll records, credit card payments, and accounting reports.
Include actual cash payments for payroll, rent, inventory, marketing, utilities, taxes, equipment, and relevant debt obligations.
Avoid counting credit card purchases and their subsequent payments twice.
The IRS recommends maintaining transaction records that identify income sources and business expenses.
Internal Revenue Service
Step 3: Record Customer Cash Receipts
Add payments received from customers during the measurement period.
Exclude financing deposits, owner contributions, and investment proceeds from operating revenue. These increase available cash but do not demonstrate that operations can support themselves.
For businesses using accrual accounting, distinguish earned revenue from collected payments.
Step 4: Calculate the Monthly Average
Imagine a company records the following three-month totals:
- Total cash spending: $240,000
- Operating cash received: $105,000
- Net cash consumed: $135,000
Its average gross burn is $240,000 ÷ 3 = $80,000 monthly.
Average net burn is $135,000 ÷ 3 = $45,000 monthly.
This approach smooths irregular monthly spending and provides a useful starting point for financial forecasting.
Calculate Cash Runway Before Making Major Commitments
Burn rate becomes especially useful when converted into cash runway: the estimated number of months a business can continue operating with its available funds.
Cash Runway = Available Cash ÷ Monthly Net Burn Rate
Consider a business holding $300,000 in unrestricted cash while consuming $60,000 monthly.
$300,000 ÷ $60,000 = 5 months of runway.
That estimate assumes spending and incoming payments remain stable.
The Arizona State University entrepreneurship team illustrates how reducing monthly losses can extend a startup’s survival period. A business holding $36,000 increases its runway from six to nine months by lowering monthly burn from $6,000 to $4,000. Runway is therefore more than a countdown. It reveals the financial value of operational improvements.
Why a Healthy-Looking Burn Rate Can Be Misleading
A single calculation rarely captures every financial risk.
A company might report a low burn rate because customers made unusually large advance payments. Another might experience temporary cash shortages while waiting for outstanding invoices.
Equipment purchases, annual insurance premiums, seasonal inventory, and tax deadlines can also distort monthly results.
Additionally, declining cash balances do not always represent operating losses. Loan repayments, investments, and financing transactions can change cash reserves independently of everyday operating performance.
For that reason, calculate operating burn separately and reconcile it with total changes in cash.
The Small Business Administration recommends financial projections covering cash flow, income, and capital expenditures. These forecasts help business owners anticipate upcoming obligations rather than simply extending past spending patterns into the future.
Five Ways to Reduce Burn Without Damaging Growth
Reducing cash consumption does not always mean cutting every available expense.
Choosing the right workspace can also influence a company’s recurring overhead, making it useful to compare coworking spaces vs. private offices when evaluating rental commitments, facilities, and operational costs.
- Audit recurring costs. Review software subscriptions, unused services, insurance contracts, and overlapping vendor agreements.
- Accelerate customer collections. Send invoices promptly, establish payment deadlines, and consider deposits for projects requiring significant upfront spending.
- Control expansion costs. Evaluate new hires, equipment purchases, and office commitments against realistic revenue forecasts.
- Improve inventory planning. Avoid tying up working capital in merchandise that may remain unsold for months.
- Evaluate spending by its return. Protect investments that genuinely improve customer retention, profitability, or operational efficiency.
Unnecessary convenience purchases can gradually weaken financial reserves. Identifying convenience spending traps during a busy workweek can help owners recognize spending habits that provide little lasting business value.
Research discussed by the Wharton School highlights an important distinction: excessive spending and excessive cost-cutting can both weaken startup survival prospects. The goal is balanced investment, not simply the lowest possible expenditure.
Build a Burn Rate Monitoring Habit
Review gross burn, net burn, and remaining runway at least monthly. Businesses experiencing unstable receipts or particularly short runway may benefit from weekly reviews.
Compare actual figures against a rolling cash forecast that includes upcoming bills, expected customer collections, and planned investments.
Also prepare conservative scenarios. What happens if customer payments fall 20%? How much runway remains if payroll increases?
Simple scenario testing turns a historical calculation into a practical decision-making tool.
Frequently Asked Questions
1. What is a good burn rate for a small business?
There is no universal target. A manageable burn rate depends on available cash, predictable revenue, operating expenses, growth plans, and the time needed to become cash-flow positive.
2. Can a profitable company have a high burn rate?
Yes. Profitability includes accounting adjustments and unpaid transactions. A company can report profits while experiencing cash shortages caused by delayed customer payments or major purchases.
3. How often should businesses calculate burn rate?
Monthly reviews work for many companies. Startups with limited cash reserves or unpredictable expenses should consider weekly monitoring alongside short-term cash forecasts.
4. Does a zero burn rate mean a business is financially secure?
Not necessarily. Breaking even on cash movements does not guarantee sufficient reserves for emergencies, upcoming debt payments, taxes, or future expansion.
The Real Value of Knowing Your Numbers
Burn rate is not merely a financial figure to present to investors. It is an early warning system that reveals whether a company’s ambitions match its available resources.
A business spending $60,000 more than it collects each month has a decision to make, regardless of how promising its sales pipeline appears.
The strongest financial plans combine accurate cash records, realistic revenue expectations, thoughtful expense management, and regular forecasting. Owners who understand their financial runway can negotiate, adjust operations, and pursue growth before circumstances force their decisions.
The essential lesson is simple: cash reserves create opportunity, but knowing how quickly they disappear creates control.